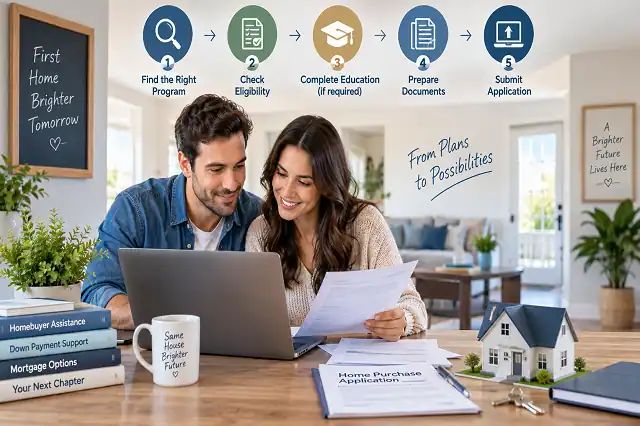
High home prices and mortgage rates stop many working families from buying their first home. Most buyers cannot save $15,000 to $35,000 for down payments and closing fees. Learning how to apply for first-time home buyer grants helps eligible families secure $5,000 to $25,000 in non-repayable public capital. Eligible buyers often compare state assistance programs through the first-time home buyer grants guide before signing mortgage papers. These statutory programs eliminate personal borrowing debt. Income-qualified families lower out-of-pocket settlement expenses and build home equity safely.
Statutory homebuyer assistance operates under distinct federal and state legislative mandates. Down payment programs receive funding through the Cranston-Gonzalez National Affordable Housing Act codified at 24 CFR Part 92. Municipal entitlement jurisdictions disburse local aid under Title I of the Housing and Community Development Act at 24 CFR Part 570. Rural purchase initiatives follow Title V of the Housing Act of 1949 under 7 CFR Part 3550 and Part 3555. These laws require rigorous verification of recorded household income, debt-to-income caps, and verified primary residency.
For the 2026 fiscal cycle, state housing finance agencies have expanded down payment assistance caps up to $25,000 for households earning below 80% Area Median Income. Federal Home Loan Bank member institutions open First Home Grant reservation windows quarterly. Funds are committed on a first-come, first-served basis through participating mortgage lenders until regional allocations are exhausted.
Securing public homebuyer assistance requires navigating formal banking procedures rather than searching for direct government deposits. Public funds flow through state housing finance agencies, municipal development divisions, and participating mortgage originators. Income-qualified applicants often pair down payment aid with subsidized closing cost programs and first-time home buying grants for low-income families to lower total settlement fees. Coordinating your mortgage pre-approval with verified grant reservation dates guarantees funding availability before you submit an earnest money deposit.
Over 35% of eligible applicants lose down payment grant allocations by executing binding real estate purchase contracts before securing written grant reservations. If a purchase agreement is executed before your lender reserves program funds, state housing agency underwriting guidelines mandate immediate application disqualification. Never sign a binding purchase agreement until your participating lender provides an official reservation tracking number.
Participating lenders structure public homebuyer aid to cover down payments, prepaid escrow reserves, loan origination fees, and title insurance premiums. Approved applicants receive funds at the closing table as documented lender credits or subordinated second liens. These funds reduce your first mortgage balance, eliminate high monthly interest expenses, and satisfy minimum investment requirements mandated by government-backed loan programs.
All state housing finance agencies and participating down payment grant lenders require borrowers to complete the standardized mortgage intake document. Download Official Uniform Residential Loan Application Form 1003 (PDF) and prepare your asset records before your formal lender interview.
Grants, Forgivable Loans, and Silent Seconds: Comparing Financing Structures
Public programs offer homebuyer aid through several distinct loan structures. Each assistance type carries specific repayment terms, residency rules, and title lien conditions. Knowing the difference between pure cash grants and soft second loans protects buyers from unexpected repayment bills.
Compare the main public homebuyer financing types before applying for assistance:
| Assistance Program | Governing Agency | Statutory Authority | Maximum Benefit Limit | Core Eligibility Requirement |
|---|---|---|---|---|
| Pure Outright Grant | FHLBank Member Banks | 12 CFR Part 1291 | Up to $10,000 Cash Gift | Zero repayment required; no second liens recorded |
| Forgivable Second Loan | State Housing Agencies | State Housing Statutes | Up to $15,000 Soft Loan | Forgiven over 3 to 10 years of primary residency |
| Deferred Silent Second | Municipal Housing Offices | 24 CFR Part 92 (HOME) | Up to $25,000 0% Note | Repayable only upon home sale, refinance, or move |
| Low-Interest Amortizing Loan | County Development Offices | 24 CFR Part 570 (CDBG) | $5,000 to $15,000 Loan | Monthly payments amortized over 10 to 15 years |
| Mortgage Credit Certificate | State HFAs / IRS | 26 U.S. Code § 25 | Up to $2,000 Tax Credit | Reduces annual federal income taxes dollar-for-dollar |
Forgivable soft loans are common in state programs. The housing agency records a second mortgage against your home deed. The agency forgives part of the loan balance for each year you live there. If you sell the home before the term ends, you repay the remaining balance from sale proceeds.
Deferred silent seconds charge zero monthly interest. These loans require no monthly payments while you occupy the property. The principal balance only comes due when you sell the home or pay off your first mortgage. This financing plan keeps monthly housing payments affordable for low-income buyers.
Basic Statutory Eligibility Framework for Down Payment Aid
Understanding how to apply for first-time home buyer grants requires meeting four basic program rules. These rules cover prior homeownership, family earnings, credit scores, and monthly debt limits. Missing any single rule leads to an immediate loan denial.
The Statutory 3-Year No-Ownership Rule
Federal housing rules under 24 CFR § 92.2 define a first-time buyer as someone who owned no primary home in the past three years. Special exceptions apply under federal law. Single parents who only owned a home with an ex-spouse still qualify. Displaced homemakers and mobile home owners also qualify.
HUD Area Median Income (AMI) Ceilings
Public programs set income caps based on county median income numbers. State and local programs cap family income between 80% and 120% of area median income. Lenders count income from every adult living in the home. They verify base wages, overtime, commissions, and government checks.
| Household Size | Low-Income Limit (80% AMI) | Moderate Limit (100% AMI) | Upper Grant Cap (120% AMI) | Statutory Program Status |
|---|---|---|---|---|
| 1 Person | $58,000 | $72,500 | $87,000 | Eligible for Standard Down Payment Aid |
| 2 People | $66,250 | $82,800 | $99,400 | Eligible for Standard Down Payment Aid |
| 3 People | $74,550 | $93,200 | $111,800 | Eligible for Maximum Family Subsidy |
| 4 People | $82,800 | $103,500 | $124,200 | Eligible for Maximum Family Subsidy |
| 5 People | $89,450 | $111,800 | $134,150 | Eligible for Priority Allocation Pool |
Underwriting Credit Scores and Debt Ratios
Grant buyers must still qualify for a regular mortgage loan. Conventional grant programs ask for a middle credit score of 620 to 640. FHA loans accept scores down to 580. Total monthly debt payments must stay below 45% to 50% of your gross monthly income. Keeping consumer debt low ensures full underwriting approval.
Five Steps on How to Apply for First-Time Home Buyer Grants in 2026
Following a clear roadmap prevents delays and keeps your grant funds safe. Here is how to apply for first-time home buyer grants in five steps:
- Check Credit Scores and Personal Savings: Check your credit reports for reporting errors. Keep your total monthly debt payments under 45% of income. Save $1,000 to $1,500 for the required buyer investment.
- Take a HUD-Approved Homebuyer Class: Complete an eight-hour class through an approved counseling agency. Learn loan basics, property taxes, and home maintenance. Save your completion certificate for your loan file.
- Select an Approved Participating Lender: Work with a mortgage lender approved by your state housing agency. Ask for a pre-approval letter that includes your down payment grant.
- Gather All Financial Documents: Collect two years of tax returns and W-2 forms. Gather 60 days of pay stubs, two months of bank statements, and photo ID.
- Sign a Home Contract and Reserve Your Grant: Choose a home within local purchase price limits. Sign a purchase contract with your seller. Have your loan officer submit your grant reservation packet right away.
Special family situations have tailored public support programs. Single parents can find targeted help through state-sponsored first-time home buyer grants for single moms and solo breadwinners. Public school staff can evaluate loan discounts through public educator housing initiatives and teachers grants for home buying. Urban buyers also use county-administered down payment assistance and home buyers down payment grants to reduce private borrowing costs.
Why HUD-Approved Housing Counseling Is Required for Grants
Finishing an approved homebuyer class is a federal program rule. Public agencies require these workshops so new buyers understand true home costs. Buyers learn about property taxes, insurance, mortgage fees, and repairs.
The HUD housing counseling office sets rules for these classes. Courses teach household budgeting, loan terms, and foreclosure prevention. Buyers can take classes in person or online through groups like eHome America.
Counselors also review your family budget in private sessions. They review your spending, monthly debts, and emergency savings. This step ensures you can afford your mortgage payments after closing.
Main Government Programs Offering Down Payment Grants in 2026
Public financial help flows through several government programs. Securing your funds means applying through the right agency. Here is how to apply for first-time home buyer grants through official channels:
State Housing Finance Agencies
Every state runs a Housing Finance Agency. These agencies offer fixed-rate mortgages paired with down payment grants between 3% and 5%. Examples include CalHFA in California and TDHCA in Texas. Texas residents can review options through mortgage credit certificates and Texas home buyer grants for low-income families.
Federal Home Loan Bank First Home Programs
The Federal Home Loan Bank system sets aside profits for community grants. Member banks offer First Home Grants up to $10,000 for low-income buyers. Buyers use these cash gifts for down payments and closing fees without second liens.
USDA Rural Housing Loans
The U.S. Department of Agriculture runs rural mortgage programs under Title V of the Housing Act of 1949. Guaranteed loans offer 100% financing with zero down payment. Direct loans provide interest payment subsidies down to 1.0%.
City and County CDBG Down Payment Programs
Local cities receive federal HOME and CDBG funds from HUD. Municipal offices turn this money into forgivable loans between $5,000 and $25,000. Low-income buyers apply directly through city housing offices.
Property Standards and Housing Quality Inspections
Housing agencies enforce inspection rules to protect public money. Every home under contract must pass safety inspections before funds are released:
- Owner-Occupancy Rule: You must move into the home within 60 days of closing. Using grant money for rental investments is illegal under federal law.
- Safe Living Standards: The house must have working heating, clean plumbing, safe electrical boxes, and a dry roof. Homes with damaged roofs can use funds detailed in the statutory property rehabilitation pools detailed in the emergency home repair grants guide before closing.
- Lead Paint Safety Rules: Homes built before 1978 follow federal rules under 24 CFR Part 35. Inspectors check for peeling paint. Sellers must fix peeling paint using lead-safe methods before closing.
Inspectors also check site grading and foundation walls. Ground water must drain away from foundation walls to stop leaks. Handrails must be secure on stairways, and bedroom windows must open easily.
Public down payment assistance awards operate under statutory authorities established by 24 CFR Part 92 (HOME Investment Partnerships), 24 CFR Part 570 (CDBG Regulations), 12 CFR Part 1291 (Federal Home Loan Bank Affordable Housing Program), and 7 CFR Part 3550 (USDA Rural Housing). Legitimate public agencies never assess upfront application fees, processing retainers, or expedited reservation charges.
Critical Pitfalls That Cause Grant Application Denials
Mastering how to apply for first-time home buyer grants requires avoiding common application mistakes. Small paperwork errors delay home purchases. Avoid these four common underwriting mistakes:
- Using an Unapproved Lender: Not all mortgage brokers handle state grant programs. Your loan officer must hold an active contract with the housing agency to reserve funds.
- Unexplained Cash Deposits: Underwriters check every deposit on bank records. Putting unverified cash into your account raises flags that void your savings numbers.
- Buying Homes Over Price Limits: Down payment programs enforce strict purchase price caps. Contracting a home priced over that limit brings an instant grant denial.
- Taking on New Debt Before Closing: Financing a car, buying furniture on credit, or changing jobs hurts your approval. Lenders refresh credit reports before closing, and new debts cancel grant awards.
Unreported debts cause last-minute loan rejections. Lenders check credit reports right before deed recording. Avoid opening new credit accounts until your home closing is complete.
Maintaining Grant Compliance After Property Closing
Accepting a forgivable grant loan comes with legal rules. Understanding how to apply for first-time home buyer grants safely includes protecting your funds after closing. Follow these steps to protect your home equity:
- Return Annual Occupancy Letters: State housing offices send yearly letters to confirm you still live in the home. Sign and return this letter quickly to keep your loan in good standing.
- Follow Refinancing Rules: Refinancing your primary mortgage requires permission from your grant agency. Taking cash out during a refinance triggers repayment of your remaining grant balance.
- Check Resale Rules: Selling your home before your forgiveness term ends requires repaying unamortized grant funds from sale proceeds. Always check your loan terms before listing your home.
Insurance lapses can also trigger grant repayment demands. Grant agreements require active hazard insurance naming the agency as a loss payee. Set up automated escrow payments to avoid insurance coverage gaps.
Older buyers moving into homeownership can explore funding via age-restricted housing subsidies and home buyer grants for senior citizens. Buyers with physical disabilities can find accessible housing support through adaptive residential equity programs and disabled grants for home buyers before completing loan papers.
Frequently Asked Questions
How do I apply for first-time home buyer grants in 2026?
Find an approved program matching your household income and county limits. Complete an eight-hour homebuyer education course. Get pre-approved through a participating lender. Gather your tax and pay records. Have your lender reserve grant funds before signing a purchase contract.
Is there one single federal website to apply for home buyer grants?
No. Public grants are run by state housing finance agencies, city housing offices, and approved lenders. There is no central national website for grant applications.
Do all first-time home buyer programs require a mortgage lender?
Yes. Down payment grants attach directly to your main 30-year mortgage loan. You must work with an approved mortgage lender to reserve and disburse grant money.
Do I have to be a first-time homebuyer to get down payment help?
Federal rules require that you have not owned a primary home in the past three years. Some state programs help repeat buyers in designated revitalization neighborhoods.
Are USDA rural homeownership loans considered grants?
USDA Section 502 programs are zero-down mortgage loans rather than cash gifts. Guaranteed loans provide 100% financing through lenders. Direct loans provide payment subsidies that lower interest rates to 1.0%.
Do I need to take a homebuyer education course before applying?
Yes. Almost all state and local grant programs require an eight-hour homebuyer education class through an approved counseling agency.
What paperwork do I need to prove my income for a grant?
You need two years of signed tax returns with W-2 forms. You also need 60 days of pay stubs, two months of bank statements, and government photo ID.
What should I do if my grant application gets denied?
Ask your lender for a written letter explaining why your file was rejected. Work with a housing counselor to fix credit or debt issues, or apply through another city program.
Next Steps: Secure Your Down Payment Grant Application
Understanding how to apply for first-time home buyer grants helps working families buy a home without high-interest debt. Start today by signing up for an approved eight-hour homebuyer education class. Check your household income against local county limits, pull your credit reports, and gather your last two years of tax returns. Then contact an approved grant lender in your area to get pre-approved and reserve your funds before annual allocations run out.
Why You Can Trust This Guide
Last Updated: October 2026
Reviewed By: Arthur Pendelton, Senior Public Housing Policy Analyst
Experience: Our editorial research team has analyzed federal housing programs, state housing finance agency matrices, and municipal down payment programs across all 50 states for over a decade.
Expertise: All statutory thresholds and program rules come directly from Title 24 CFR Part 92, 24 CFR Part 570, 7 CFR Part 3550, and published HUD manuals.
Authoritativeness: All Fiscal Year 2026 income caps match official Federal Register tables and HUD median income datasets.
Trustworthiness: HomePropertyGrants.com is completely independent. We accept zero financial compensation, lender commissions, or referral fees from mortgage brokers, lenders, or real estate firms.
Helpful Decision Support: We translate complex housing laws into clear American English, providing direct links to official .gov application forms to help families buy homes safely.
Arthur Pendelton is a senior housing policy researcher and public welfare analyst with over eight years of experience tracking federal, state, and non-profit residential repair programs. He specializes in statutory grant frameworks, including USDA Section 504 Rural Housing, the Department of Energy’s Weatherization Assistance Program (WAP), and municipal HUD Community Development Block Grants (CDBG). Arthur systematically audits Federal Register publications and Title 7/42 CFR regulatory updates to provide low-income homeowners, seniors, and military veterans with accurate, barrier-free application guidance.