How to Apply For First-Time Home Buyer Grants: 5 Easy Steps
High home prices and high interest rates make it hard for working families to buy their first home. Most buyers cannot save $15,000 to $35,000 for a down payment and closing costs. Learning how to apply for first-time home buyer grants helps eligible families get $5,000 to $25,000 in free public money. Smart buyers look at state programs in the first-time home buyer grants guide before they sign any bank papers. These government programs wipe out personal debt. Low-income families pay less cash up front and build home value safely.
Government homebuyer help follows strict federal and state laws. Down payment programs get money from the Cranston-Gonzalez Act under Title 24 rules. City offices give out local help under the Housing and Community Development Act. Country buying programs follow Title 5 of the Housing Act of 1949 under Title 7 rules. These laws say workers must check your exact income, your monthly debt, and where you live.
For the 2026 budget year, state housing offices have raised down payment limits up to $25,000 for families making below 80% of the county limit. Federal Home Loan Banks open grant windows four times a year. The money goes to whoever applies first through approved banks until the money runs out.
Getting public homebuyer help means you must go through a bank, not look for a direct government check. Public money flows through state housing offices, city desks, and approved mortgage lenders. Low-income buyers often mix down payment help with subsidized closing cost programs and first-time home buying grants for low-income families to pay less at the closing table. Making sure your bank locks in your grant before you put down cash protects your money.
Over 35% of buyers lose their grant money because they sign a house contract before the bank locks in their grant. If you sign a buying contract before your lender saves your grant, state rules will cancel your application right away. Never sign a house contract until your lender gives you an official grant tracking number.
Approved lenders use public homebuyer money to pay for down payments, closing fees, loan costs, and title insurance. Approved buyers get the money at the closing table as a bank credit or a special second loan. This money lowers your main loan amount, stops high monthly interest, and meets the cash rules for government-backed loans.
All state housing offices and approved grant lenders make you fill out a standard mortgage form. You can download the Official Uniform Residential Loan Application Form 1003 (PDF) and get your bank papers ready before your big bank meeting.
Grants, Loans, and Silent Seconds: Knowing the Difference
Public programs offer homebuyer money in a few different ways. Each kind has special rules about paying it back, staying in the house, and holding onto your deed. Knowing the difference between free cash grants and special second loans protects buyers from surprise bills later.
Compare the main public homebuyer money types before you apply:
| Assistance Program | Governing Agency | Statutory Authority | Maximum Benefit Limit | Core Eligibility Requirement |
|---|---|---|---|---|
| Pure Outright Grant | FHLBank Member Banks | Title 12 Federal Rules | Up to $10,000 Cash Gift | Zero repayment required; no second holds on deed |
| Forgivable Second Loan | State Housing Agencies | State Housing Laws | Up to $15,000 Special Loan | Goes away if you stay in the home for 3 to 10 years |
| Deferred Silent Second | City Housing Offices | Title 24 Federal Rules | Up to $25,000 0% Loan | You only pay it back if you sell, move, or refinance |
| Low-Interest Amortizing Loan | County Housing Offices | Title 24 Federal Rules | $5,000 to $15,000 Loan | Monthly payments spread over 10 to 15 years |
| Mortgage Credit Certificate | State HFAs / IRS | U.S. Tax Code | Up to $2,000 Tax Credit | Lowers your federal taxes dollar-for-dollar every year |
Special loans that go away are very common in state programs. The housing office puts a second loan hold on your house deed. The office wipes out part of the loan balance for every year you live there. If you sell the house before the time is up, you must pay the rest of the loan from the money you make on the sale.
Silent second loans charge zero interest. You make zero monthly payments while you live in the house. You only have to pay it back when you sell the house or pay off your first mortgage. This keeps monthly house bills cheap for low-income buyers.
Basic Rules to Qualify for Down Payment Help
Understanding how to apply for first-time home buyer grants means you must meet four main program rules. These rules check if you owned a home before, how much money your family makes, your credit score, and your monthly debt. Failing even one rule means your loan gets denied right away.
The 3-Year No-Ownership Rule
Federal housing rules say a first-time buyer is someone who has not owned a main home in the last three years. There are some special exceptions. Single parents who only owned a home with an ex-spouse still count as first-time buyers. Stay-at-home parents starting over and mobile home owners also qualify.
HUD County Income Limits
Public programs cap your income based on what a normal family makes in your county. State and local programs cap family income between 80% and 120% of the county average. Banks count the money made by every adult living in the house. They check your base pay, overtime, bonuses, and government checks.
| Household Size | Low-Income Limit (80% AMI) | Moderate Limit (100% AMI) | Upper Grant Cap (120% AMI) | Statutory Program Status |
|---|---|---|---|---|
| 1 Person | $58,000 | $72,500 | $87,000 | Eligible for Standard Down Payment Aid |
| 2 People | $66,250 | $82,800 | $99,400 | Eligible for Standard Down Payment Aid |
| 3 People | $74,550 | $93,200 | $111,800 | Eligible for Maximum Family Subsidy |
| 4 People | $82,800 | $103,500 | $124,200 | Eligible for Maximum Family Subsidy |
| 5 People | $89,450 | $111,800 | $134,150 | Eligible for Priority Allocation Pool |
Credit Scores and Monthly Debt Limits
Grant buyers must still qualify for a normal bank loan. Most grant programs want a middle credit score of 620 to 640. FHA loans take scores down to 580. Your total monthly debt payments cannot be more than 45% to 50% of your gross monthly pay. Keeping your credit card debt low helps you get fully approved.
Five Steps on How to Apply for First-Time Home Buyer Grants in 2026
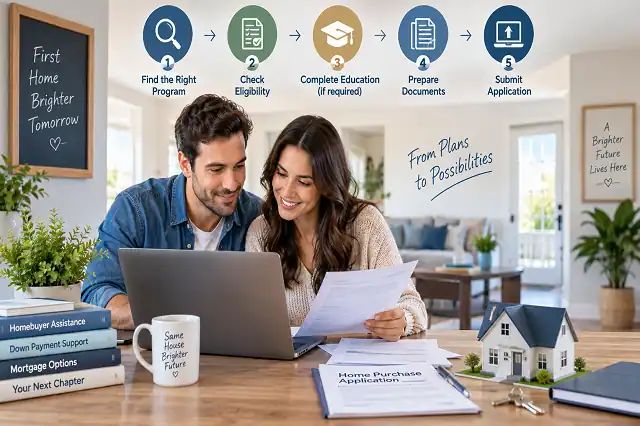
Following a clear list stops delays and keeps your grant money safe. Here is how to apply for first-time home buyer grants in five steps:
- Check Credit Scores and Savings: Check your credit reports for mistakes. Keep your total monthly debt under 45% of your pay. Save $1,000 to $1,500 of your own money for the required buyer investment.
- Take an Approved Homebuyer Class: Finish an eight-hour class through a real counseling office. Learn about loans, property taxes, and fixing a house. Keep your certificate paper for your bank file.
- Pick an Approved Bank: Work with a mortgage lender approved by your state housing office. Ask for a pre-approval letter that includes your down payment grant.
- Get All Money Papers Ready: Get two years of tax returns and W-2 forms. Get 60 days of pay stubs, two months of bank statements, and your photo ID.
- Sign a Contract and Lock in the Grant: Pick a house that fits the local price limit. Sign a buying contract with the seller. Have your loan officer lock in your grant money right away.
Special families can get special help programs. Single parents can find help through state-sponsored first-time home buyer grants for single moms. Public school teachers can check loan discounts through public educator housing initiatives and teachers grants for home buying. City buyers also use county-administered down payment assistance and home-buying grants to lower bank costs.
Why You Must Take a Homebuyer Class for Grants
Finishing an approved homebuyer class is a strict federal rule. Public offices make you take these classes so you understand the real costs of owning a house. Buyers learn about property taxes, insurance, bank fees, and repairing the house.
The HUD housing counseling office makes the rules for these classes. The classes teach you how to budget, understand loan terms, and avoid losing your house to the bank. Buyers can take classes in person or online through groups like eHome America.
Counselors also look at your family budget in a private meeting. They look at your spending, monthly debts, and emergency savings. This step proves you can pay your mortgage bill after you buy the house.
Main Government Programs for Down Payment Money in 2026
Public financial help flows through different government programs. Getting your grant money means you must apply at the right office. Here is how to apply for first-time home buyer grants through the official doors:
State Housing Finance Agencies
Every state has its own Housing Finance Agency. These state offices offer normal mortgage loans matched with down payment grants between 3% and 5% of the house price. Examples are CalHFA in California and TDHCA in Texas. Texas families can look at mortgage credit certificates and Texas home buyer grants for low-income families.
Federal Home Loan Bank Programs
The Federal Home Loan Bank system saves a piece of its profits for community grants. Member banks give First Home Grants up to $10,000 for low-income buyers. Buyers use this free cash for down payments and closing fees without any second loan holds on their deed.
USDA Rural Housing Loans
The U.S. Department of Agriculture runs country mortgage programs using Title 5 rules. Guaranteed loans give you 100% financing, so you do not need a down payment. Direct loans give you special help to lower your interest rate all the way down to 1.0%.
City and County CDBG Down Payment Programs
Local cities get federal HOME and CDBG money from HUD. City housing offices turn this money into special loans between $5,000 and $25,000 that slowly go away. Low-income buyers apply straight through the city housing office.
House Safety and City Quality Checks
Housing offices use strict rules to protect public money. Every house you want to buy must pass a safety check before they give you the cash:
- Living in the House Rule: You must move into the home within 60 days of closing. Using grant money to buy a rental house to make money is against federal law.
- Safe Living Rules: The house must have a working heater, clean pipes, safe electrical boxes, and a roof that does not leak. If a house needs big repairs before you close on the loan, read the statutory property rehabilitation pools detailed in the emergency home repair grants guide.
- Lead Paint Safety Rules: Houses built before 1978 must follow strict federal rules under Title 24. Inspectors check for peeling paint. The seller must fix any peeling paint safely before you close on the house.
Inspectors also check the dirt around the house and the basement walls. Rainwater must flow away from the house to stop leaks. Handrails on stairs must be tight, and bedroom windows must open easily so you can get out in a fire.
Public down payment money follows strict federal laws, like Title 24, Title 12, and Title 7. Real government offices never charge you money to apply, process your file, or hold your spot in line.
Big Mistakes That Get Your Grant Rejected
Knowing how to apply for first-time home buyer grants means dodging common mistakes. Small paperwork errors can delay buying your home. Avoid these four common mistakes that ruin your loan approval:
- Using a Bank Not on the List: Not every bank works with state grant programs. Your loan officer must have a real contract with the housing office to lock in your money.
- Secret Cash Deposits: Bank workers check every single deposit in your checking account. Dropping random cash into your account without proof raises red flags and ruins your savings numbers.
- Buying a House Too Expensive: Down payment programs set a hard limit on the house price. Signing a contract for a house over that limit gets your grant denied right away.
- Getting New Debt Before Closing: Buying a new car, charging furniture on a credit card, or changing jobs will ruin your loan. Banks check your credit score again right before closing, and new debt cancels your grant.
Hiding debts causes last-minute loan rejections. Lenders check your credit reports right before they sign the deed. Do not open any new credit cards or loans until your house closing is totally finished.
Keeping Your Grant Safe After You Buy the House
Taking a special loan that goes away comes with legal rules. Knowing how to apply for first-time home buyer grants safely means protecting your money after closing. Follow these steps to keep your home equity safe:
- Return the Yearly Letter: State housing offices send a letter every year to make sure you still live in the house. Sign and send this letter back fast to keep your loan safe.
- Follow the Refinance Rules: Changing your main mortgage (refinancing) needs permission from your grant office. If you take cash out of your house during a refinance, you must pay back the rest of the grant money.
- Check the Selling Rules: If you sell your house before your time is up, you must pay back the leftover grant money from your sale profits. Always read your loan rules before you put your house up for sale.
Letting your house insurance lapse can also make the office demand their money back. Grant contracts say you must keep active insurance that names the office on the policy. Set up automatic bank payments so your insurance never turns off.
Older buyers looking for their first home can check out age-restricted housing subsidies and home buyer grants for senior citizens. Buyers with physical disabilities can find special accessible homes through adaptive residential equity programs and disabled grants for home buyers before signing their loan papers.
Frequently Asked Questions
How do I apply for first-time home buyer grants in 2026?
Find an approved program that fits your family income and your county limits. Take an eight-hour homebuyer class. Get pre-approved by a bank on the list. Gather your tax papers and pay stubs. Have your bank lock in the grant money before you sign a contract for the house.
Is there one single federal website to apply for home buyer grants?
No. Public grants are run by state housing offices, city housing desks, and approved banks. There is no one big national website to fill out a form.
Do all first-time home buyer programs need a mortgage lender?
Yes. Down payment grants attach right to your main 30-year bank loan. You must work with an approved bank to get the grant money.
Do I have to be a first-time homebuyer to get down payment help?
Federal rules say you must not have owned a main house in the past three years. Some state programs will help repeat buyers if they buy in special run-down neighborhoods.
Are USDA rural home loans considered free grants?
USDA Section 502 programs are zero-down loans, not free cash gifts. Guaranteed loans give you 100% financing through a bank. Direct loans give you special help to drop your interest rate down to 1.0%.
Do I have to take a homebuyer class before applying?
Yes. Almost all state and local grant programs say you must take an eight-hour homebuyer class through an approved teaching office.
What papers do I need to prove my income for a grant?
You need your signed tax returns from the last two years with W-2 forms. You also need 60 days of pay stubs, two months of bank statements, and a government photo ID.
What should I do if my grant gets denied?
Ask your bank for a written letter explaining exactly why they said no. Work with a housing counselor to fix credit or debt mistakes, or try applying at a different city program.
Next Steps: Get Your Down Payment Grant Application Ready
Knowing how to apply for first-time home buyer grants helps working families buy a home without bad, high-interest debt. Start today by signing up for an approved eight-hour homebuyer class. Check your family income against the county limits, check your credit report, and get your last two years of tax returns. Then call an approved grant lender in your town to get pre-approved and lock in your money before it runs out for the year.
Why You Can Trust This Guide
Last Updated: November 2026
Reviewed By: Arthur Pendelton, Senior Public Housing Policy Analyst
Experience: Our team has studied federal housing rules, state housing programs, and city down payment grants across all 50 states for over ten years.
Expertise: All dollar limits and program rules come straight from real federal laws, like Title 24, Title 12, Title 7, and official HUD rulebooks.
Authority: All 2026 income limits match real Federal Register charts and official HUD income numbers.
Trustworthiness: HomePropertyGrants.com works totally alone. We never take money, bank fees, or favors from mortgage brokers, lenders, or real estate agents.
Helpful Decision Support: We explain hard housing laws in simple American English and give you direct links to real .gov forms to help families buy homes safely.
Arthur Pendelton is a senior housing policy researcher and public welfare analyst with over eight years of experience tracking federal, state, and non-profit residential repair programs. He specializes in statutory grant frameworks, including USDA Section 504 Rural Housing, the Department of Energy’s Weatherization Assistance Program (WAP), and municipal HUD Community Development Block Grants (CDBG). Arthur systematically audits Federal Register publications and Title 7/42 CFR regulatory updates to provide low-income homeowners, seniors, and military veterans with accurate, barrier-free application guidance.